For UK retail, hospitality, and service businesses that rely heavily on card payments, maintaining steady cash flow can be a constant balancing act. Seasonal trading fluctuations, unexpected equipment repairs, or sudden stock purchasing opportunities often require fast funding without the rigid commitment of standard monthly bank repayments. A merchant cash advance (MCA) has emerged as one of the most flexible alternative finance options available to small and medium enterprises. Rather than structured as a conventional loan, an MCA allows a business to raise upfront capital against its future card sales, repaying the funds automatically as customers pay by card.
How Does a Merchant Cash Advance Work?
A merchant cash advance is an advance on future revenue. A finance provider supplies a lump sum of capital upfront, and in return, buys an agreed portion of your future credit and debit card receipts. The core characteristic of an MCA is that repayments automatically scale up or down based on your business earnings.
The Three Key Components of an MCA
To understand the mechanics of a merchant cash advance, it helps to examine three fundamental financial terms used by providers:
Advance Amount: The lump sum of capital paid directly into your business bank account.
Factor Rate: Instead of charging an annual percentage rate (APR), lenders apply a factor rate - typically between 1.1 and 1.4 - to determine the total cost of borrowing.
Holdback Rate: The fixed percentage (usually between 5% and 20%) deducted from your daily or weekly card processor settlements until the advance is paid off.
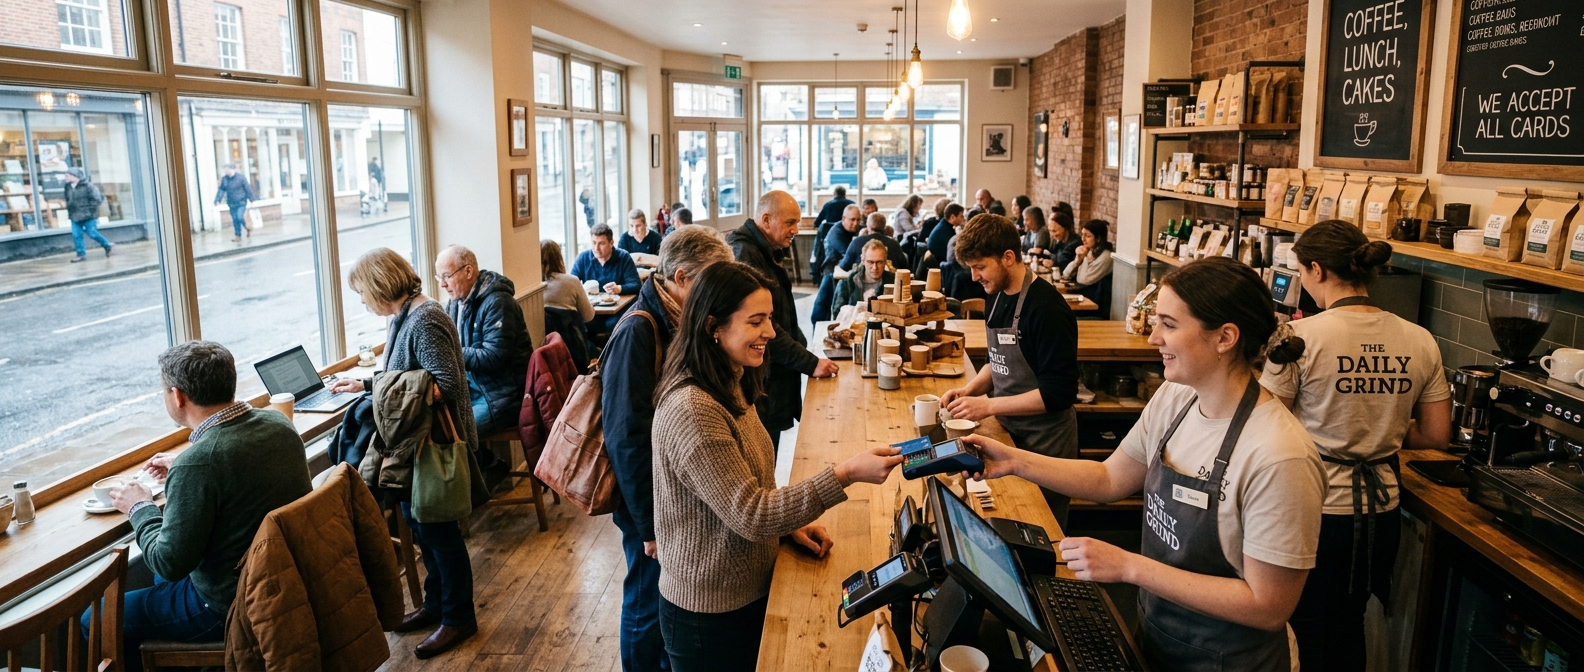
The repayment process is fully automated. When a customer pays for goods or services using a card terminal (PDQ machine) or online payment gateway, the card processor splits the transaction. The agreed holdback percentage goes automatically to the MCA provider, while the remaining balance enters your business bank account. During a busy sales period, you clear the advance faster. If trading slows down, daily repayments decrease proportionally, relieving pressure on your working capital.
Merchant Cash Advance vs Traditional Business Loan
Choosing between a merchant cash advance and a standard business loan comes down to cash flow predictability, required speed of funding, and available assets. Traditional term loans require fixed monthly repayments regardless of your revenue performance, whereas an MCA flexes in harmony with your turnover.
Feature | Merchant Cash Advance | Traditional Business Loan |
|---|---|---|
Repayment Structure | Flexible percentage of daily card sales | Fixed monthly instalments |
Cost Calculation | Fixed factor rate applied upfront | Compound interest rate (APR) over time |
Security Required | Unsecured (based on card sales history) | Often requires property, asset collateral, or personal guarantees |
Speed of Funding | Typically 24 to 48 hours | Several days to several weeks |
Impact of Slow Trading | Repayment amounts decrease automatically | Full fixed payment remains due |
Understanding Factor Rates and Total Repayment Costs
Because merchant cash advances do not use an annual percentage rate, understanding how much the funding will actually cost requires examining the factor rate. The factor rate is expressed as a simple decimal multiplier, usually ranging from 1.10 to 1.45 depending on the risk assessment and transaction volume of your business.
To calculate the total repayment amount, you multiply the advance sum by the factor rate. For example, if you receive an advance of £20,000 with a factor rate of 1.20, your total repayable amount will be £24,000 (£20,000 x 1.20). Unlike a traditional loan, clearing the balance early does not reduce the total fee payable, because the factor rate applies to the principal sum upfront. However, there are no penalty fees or late charges if repayments take longer due to slower sales.
Advance Amount | Factor Rate | Total Amount Repayable | Holdback Percentage | Est. Daily Card Sales | Est. Daily Repayment |
|---|---|---|---|---|---|
£10,000 | 1.20 | £12,000 | 10% | £1,000 | £100 |
£25,000 | 1.25 | £31,250 | 12% | £2,000 | £240 |
£50,000 | 1.30 | £65,000 | 15% | £4,000 | £600 |
Pros and Cons of a Merchant Cash Advance
While an MCA offers unparalleled flexibility for businesses taking card payments, it is important to evaluate both the benefits and trade-offs before securing funding.
Benefits of a Merchant Cash Advance
No Fixed Repayment Deadlines: Because repayments fluctuate with income, there is no fixed term length or danger of missing a set monthly deadline during lean trading months.
Unsecured Financing: You do not need to secure the capital against valuable physical assets like commercial property, equipment, or land.
Fast Access to Working Capital: Digital integration with payment terminals allows providers to assess card statement data rapidly, often approving funds within 24 to 48 hours.
Accessible Credit Profiling: Approval depends primarily on your card sales volume and trading consistency rather than strict personal credit scores.
Factors to Consider
Card Sales Dependence: MCAs are only suitable for businesses that process a significant portion of revenue via credit or debit card terminals or e-commerce storefronts.
Higher Effective Cost: Factor rates can make an MCA more expensive overall compared to low-interest, long-term bank facilities.
No Early Repayment Discount: Since the total fee is calculated upfront using the factor rate, clearing the advance early does not reduce the fee payable.
Eligibility Criteria for UK Businesses
Securing a merchant cash advance is generally straightforward compared to standard commercial loans. Most UK alternative lenders look for the following basic requirements:
Trading History: A minimum of 3 to 6 months of continuous active trading in the UK.
Card Payment Volume: Minimum monthly card turnover ranging between £2,500 and £5,000.
Compatible Payment System: An established card payment terminal, point-of-sale (POS) system, or online payment gateway provider.
Finding the Right Merchant Cash Advance for Your Business
Every business has unique trading patterns, cash flow cycles, and capital requirements. With dozens of alternative finance providers operating across the UK financial market, comparing factor rates, holdback percentages, and contractual terms can be complex.
SME Money connects UK businesses with specialist brokers who search over 70 lenders to find the right funding - without the bias of a single bank. By working with independent brokers who understand alternative commercial finance, you can compare multiple options and secure merchant cash advance terms tailored specifically to your turnover and cash flow needs.