Business loans
for UK SMEs
A business loan can be the boost needed for your next big step. Whether you are looking to bridge a cash flow gap, invest in new team members or fund a major expansion, having the right capital at the right time is essential.


At SMEmoney.co.uk
We give you more funding options than a traditional bank
We are not a lender or a broker. We simply refer your details to specialist broker partners, based on your requirements, who have access to over 70 UK lenders.
This ensures you get an impartial view of the market and a better chance of finding a loan that fits your business profile.
Interest rates and eligibility
Rates that reflect your business
Interest rates are not the same for everyone. They vary based on the age of your business, your business credit rating, and even your personal credit rating.
- Established Businesses: If you have several years of profitable trading, you will likely access the most competitive rates. A panel of lenders gives you more choice than your own bank alone.
- New Businesses: Startups and younger companies can attract higher rates. Lenders view newer ventures as higher risk - which is why many new businesses turn to asset finance or invoice finance first.
- Credit Rating: A strong credit score helps lower your costs, but our brokers also work with lenders who specialise in recovery finance for businesses with less-than-perfect credit.
Choosing the right loan
There are two main types of business loan
Plus specific support for new ventures. The right choice depends on your assets and how quickly you need the funds.
| Feature | Unsecured Business Loan | Secured Business Loan | Startup Loan |
|---|---|---|---|
| Collateral | No assets required as security. | Backed by property or machinery. | Often requires a personal guarantee. |
| Loan Amount | Typically up to £250,000. | Can be £1 million or more. | Usually up to £25,000 per director. |
| Speed | Very fast; often within 24 hours. | Slower; requires asset valuations. | Moderate; requires a business plan. |
| Interest Rates | Generally higher. | Typically lower. | Fixed and often subsidised. |
| Best For... | Short-term cash flow or small projects. | Large-scale long-term investments. | Businesses trading for less than 3 years. |
A closer look at your options
Unsecured business loans
This is the most popular choice for SMEs who need speed and flexibility. You do not need to put up property or equipment as collateral. Because the lender takes on more risk, the interest rates are usually higher. Most lenders will require a personal guarantee from the directors.
A closer look at your options
Secured business loans
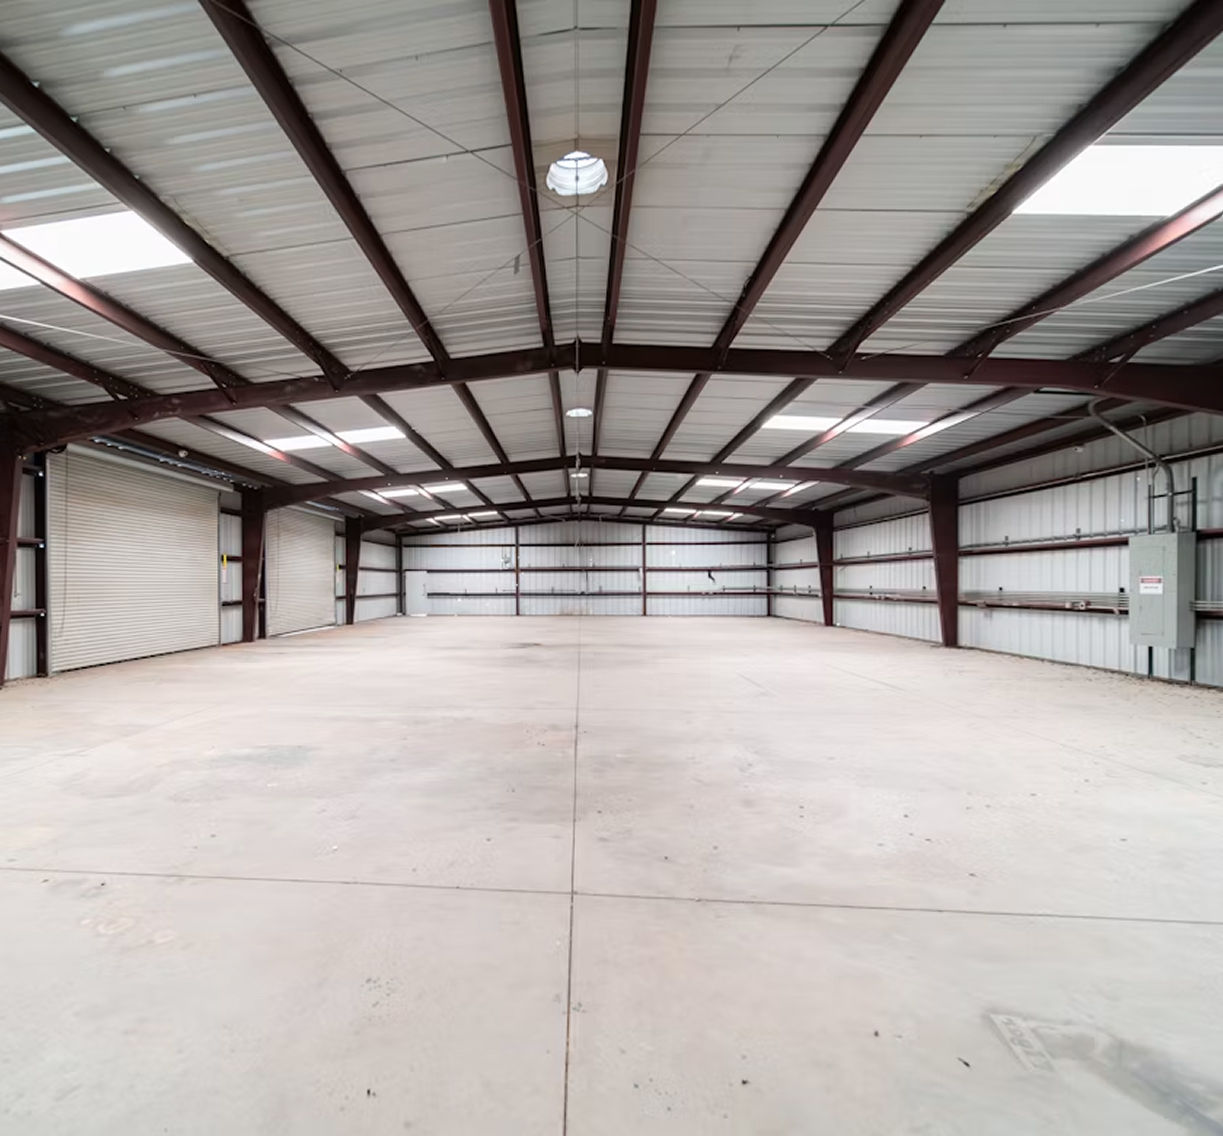
If you need a larger sum of money, a secured loan is often the answer. By using a business asset like a warehouse, office, or heavy machinery as security, you can often unlock lower interest rates and longer repayment terms. This is a strategic way to fund major acquisitions.
A closer look at your options
Startup loans
If you have been trading for less than three years, traditional loans can be hard to find. Our brokers can help you navigate startup-specific funding. These loans are designed to help you get off the ground and usually come with fixed interest rates and mentoring support.
There are also Government Guarantee Schemes, but these typically still need a personal guarantee - with the government backing the bank, not you. In the event of default, the lender will come to you first, not The Treasury.
The SMEMoney process
We have simplified the path to getting your business funded.
We don't charge an upfront fee. Your broker will need to perform a soft credit check to assess the right options for your business loan.
Calculate Your Business Loan
Use our free business loan calculator tools to estimate your monthly repayments based on current market rates.
From the SMEmoney family
Need help growing the business behind the funding?
The Fractions is our sister digital marketing and web development agency, working with founder-led SMEs turning over roughly £1m-£15m on paid advertising, customer journey optimisation, and technical growth strategies - with a particular focus on automotive and financial services.
FAQs
Frequently asked questions
No. We simply refer your details to a suitable broker from our panel, based on your requirements, who then manages the application process with the lenders.
This depends on your turnover and credit history. Unsecured loans typically range from £10,000 to £250,000, while secured loans can go much higher.
Lenders look at time in business as a sign of stability. Companies with less than two years of trading history are statistically more likely to default, so lenders charge more to cover that risk.
Yes. Our brokers have access to specialist lenders who look at your current cash flow and future potential rather than just your past credit score. There are specific lenders who operate in this market, but with higher interest rates.
Unsecured loans can often be approved and funded within 24 to 48 hours. Secured loans take longer because the assets involved must be valued.
For most standard unsecured loans, you just need your latest accounts and bank statements. Startup loans and larger secured loans will usually require a formal business plan.
This varies by lender. Your matched broker will highlight any early exit fees before you commit to a loan.
It is a commitment from a business director to personally repay the loan if the company is unable to do so. This is standard for most unsecured SME loans.
Most business loans are flexible. Common uses include hiring staff, buying stock, refurbishing premises, or managing a seasonal cash flow dip.
Yes, our calculators and introduction service are 100% free for you. We receive a fee from our broker partners only if your loan is successful.
Asset finance and invoice finance are popular options with a higher acceptance rate, as they have a lower risk for the lender as they are secured on either an asset or an invoice (debtor).